Debt Management
How to Stop Living Paycheck to Paycheck
Living paycheck to paycheck isn't usually a simple math problem of spending more than you earn — plenty of people whose spending is technically less than their income still feel like every paycheck disappears the moment it arrives. The actual mechanism is often a timing gap: expenses that come due before the next paycheck lands, forcing constant reliance on money that hasn't arrived yet.
Why This Happens at a Wide Range of Income Levels
It's tempting to assume the paycheck-to-paycheck cycle is purely about not earning enough, and for some people that's a real part of it. But the pattern shows up across a wide income range, because spending — including fixed costs like housing, a car payment, subscriptions — tends to expand to match whatever income is available. A raise without a specific plan for the extra money often just raises the baseline spending level, leaving the same zero-balance pattern at a higher number.
This matters because it means the fix isn't only "earn more" — it's building a structural buffer that breaks the timing dependency, regardless of income level.
The Real Mechanism: A Timing Gap, Not Just a Spending Gap
Consider someone whose expenses genuinely fit within their income over a full month, but who still feels perpetually behind. Often, the cause is that certain expenses come due in the days right before a paycheck arrives, forcing reliance on whatever's left from the previous paycheck — which may already be thin from other expenses earlier in that cycle.
This is a timing problem, not strictly a budget problem. The fix isn't necessarily spending less overall — it's building a buffer that removes the dependency on perfect paycheck timing.
Step 1: Get a Real Picture of the Cycle
Track exactly when income arrives and when major expenses are due, for one full pay cycle. This often reveals the specific timing gap causing the stress — a rent payment due three days before payday, for example, forcing a scramble every single month regardless of total income versus total expenses.
Step 2: Build a Small Buffer, Even Before Tackling Everything Else
A buffer of even a few hundred dollars — separate from regular spending — can absorb the timing gap identified in step 1. This is a narrower, more immediate goal than a full emergency fund; its specific purpose is breaking the paycheck-to-paycheck dependency, not covering every possible emergency.
Building this buffer usually requires a temporary, specific cut somewhere in spending — not "spend less in general," which rarely produces a concrete result, but one or two identifiable reductions for a defined period, redirected entirely toward the buffer until it's built.
Step 3: Find the Specific Leaks, Not Just "Spend Less"
A vague instruction to cut spending is hard to act on. A specific review of the last month's transactions usually turns up concrete targets: subscriptions that aren't being used, a recurring takeout order that's become automatic, a category that's crept up without anyone deciding it should. How to Find Unnecessary Expenses goes deeper into this process.
Redirecting even one or two specific costs toward the buffer, for a defined and limited period, tends to work better than an open-ended commitment to spend less broadly.
Step 4: Separate Fixed Costs From Flexible Ones, Honestly
Some expenses genuinely can't move in the short term — rent, a loan payment, insurance. Others feel fixed but actually have room: a subscription tier that could be downgraded, a phone plan that could be switched, a recurring service that isn't being used to its full value.
Being honest about which expenses are truly fixed and which just feel that way opens up real room to redirect money toward the buffer, without requiring a dramatic lifestyle change.
Step 5: Automate the Buffer Contribution
Once even a small amount is identified, automate its transfer to a separate account immediately after each paycheck arrives — before it has a chance to get absorbed into regular spending. Money that's "left over" at the end of a pay period, after everything else has already been spent, rarely exists in the amount hoped for.
Step 6: Use the Buffer to Break the Cycle, Not to Spend Freely
Once the buffer exists, its job is covering the timing gap identified in step 1 — letting a bill get paid from the buffer if a paycheck is running a few days behind an expense's due date, then refilling the buffer once that paycheck arrives. Treating the buffer as extra spending money defeats its purpose and puts the cycle right back where it started.
What Keeps People Stuck in the Cycle Longer Than Necessary
Assuming a raise alone will fix it. Without a specific plan for new income, spending typically rises to match it.
Trying to fix everything at once. A large, ambitious plan to overhaul spending completely is harder to sustain than one specific, identifiable change at a time.
No separate buffer account. Extra money sitting in the main checking account tends to get absorbed into regular spending before it can do its job.
Treating the buffer as available spending money. This undoes the entire structural fix and returns things to where they started.
What Breaking the Cycle Actually Looks Like
It's rarely a dramatic, sudden shift. It's usually a small buffer, built gradually, that quietly removes the constant dependency on a paycheck landing exactly on time. Once that dependency is gone, the felt experience of managing money changes significantly, even before any larger financial goals — an emergency fund, debt payoff, savings — are fully achieved.
Want a system that tracks your actual pay cycle against your expenses, so you can see exactly where the gap is instead of guessing? MoneyMap includes a full budget and expense dashboard built for exactly this kind of visibility.
Frequently asked questions
Is living paycheck to paycheck only a low-income problem?
No — it happens across a wide range of income levels. It's a structural pattern (spending, including fixed costs, expanding to match whatever comes in) more than a pure function of income size, which is why a raise alone often doesn't fix it.
What's the fastest way to break the cycle?
Building a small buffer — even a few hundred dollars — that lets one paycheck's money cover expenses that used to depend on the next one arriving on time. That timing gap is often the actual mechanism keeping the cycle going.
Does a pay raise fix living paycheck to paycheck?
Not automatically. Without a specific plan for where the extra income goes, spending commonly rises to match it, leaving the same zero-balance pattern at a higher income level.
How long does it typically take to break the cycle?
It varies widely depending on the size of the income-expense gap, but building even a one-week buffer is often achievable within a few months of deliberate, consistent effort — and that buffer alone changes the dynamic significantly.
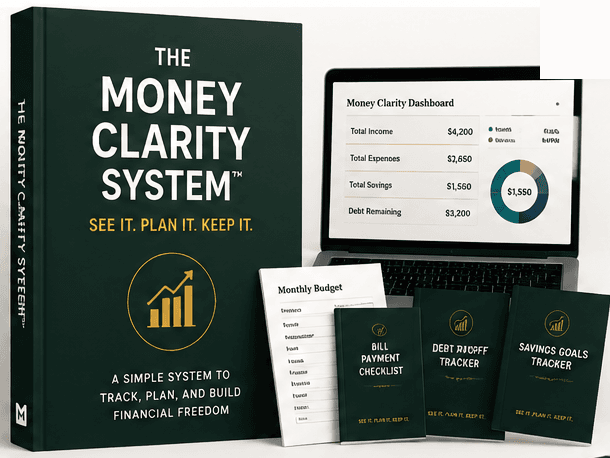
The Money Clarity System™
Ready to actually track it, not just read about it?
The full guide, dashboard, planner, challenges, and bonuses — one payment, lifetime access.
Related articles
Saving Money
How to Build an Emergency Fund (Even If You're Starting From Zero)
An emergency fund doesn't need to reach 'six months of expenses' to start protecting you. The gap between zero and a few hundred dollars matters more than most advice admits.
5 min read
Budgeting
How to Create a Monthly Budget (That Fits Your Actual Paycheck)
A monthly budget only works if it matches how income actually arrives — not a single averaged total that ignores the timing of real paychecks and real bills.
4 min read
Debt Management
How to Pay Off Credit Card Debt (A Realistic Plan)
Credit card debt is expensive specifically because of how it compounds. A payoff plan that accounts for that compounding works differently than one that doesn't.
5 min read
Budgeting
How to Stop Overspending (Without Just 'Trying Harder')
"Just spend less" rarely works because overspending usually has a specific pattern behind it — a trigger, a category, a moment in the month. Find that, and the fix gets much more specific.
4 min read